Compliance: Commentary on AML, beneficial ownership and corporate existence
Written for Law360 Canada. Each piece reads a provision to the end.
Why both halves
The reports measure the registers. The commentary argues what the measurements mean.
The CorpCentre Research Programme counts what Canada’s corporate registers actually contain — currency, beneficial ownership, the pathway out of corporate existence. The commentary takes those measurements into the statute: what a reporting entity’s obligations require, what a registry check establishes, and where the law has moved since March 2026. Each is commentary, not legal advice; several read provisions no tribunal has yet construed.
In Law360 Canada
Consulted is not verified: The limits of Canada’s beneficial-ownership register
Reporting entities must obtain beneficial-ownership information and take reasonable measures to confirm its accuracy — by a measure different from the one used to obtain it. FINTRAC recognises registry consultation as one such measure. What a register entry actually establishes is a separate question.
- Since 1 October 2025, s. 138.1 requires consultation of the federal register for high-risk CBCA clients, with material discrepancies reported within 30 days — for no other client and no other register.
- The federal register opened on 22 January 2024; Quebec began requiring ultimate beneficiaries on 31 March 2023; Alberta imposes no record-keeping obligation at all.
The PDF includes the related research bulletin after the article.
Dissolved without notice: The creditor gap in administrative strike-offs
The CBCA devotes 22 sections to winding up a corporation properly — liquidation, creditor claims, distribution of property, court supervision where needed. Most federal corporations leave the register by a different provision entirely: a certificate issued because a required filing was not made.
- Of 723,987 federal dissolutions recorded to 6 August 2026, 493,923 — 68.2% — were for non-compliance rather than by decision of the corporation.
- On Corporations Canada’s own monthly count for January to July 2026, s. 212 dissolutions were 79.1% of certificate-flow removals — nearly four for every voluntary one.
- A corporation winding itself up must notify known creditors. One dissolved for non-compliance is notified, and so are its directors; its creditors are not — and the two-year clock on their remedies runs anyway.
The PDF includes the related research bulletin after the article.
The meaning of ‘effective’: Canada’s new AML compliance-program standard
Since 26 March 2026, s. 9.6(1.1) of the PCMLTFA requires every reporting entity to ensure its compliance program is reasonably designed, risk-based and effective. Little has been written about what the provision actually adds: an express program-level performance standard.
- Section 9.6(1) is unamended and still requires a program “intended to ensure” compliance. Parliament left it in place and added the new obligation beside it.
- Each limb is independently sufficient to found a contravention — architecture, calibration to identified risks, and whether the program produces the intended compliance outcomes.
- Its schedule entry is a very serious violation: a $20 million per-violation ceiling for an entity, $4 million for a person.
The PDF includes the related research bulletin after the article.
How escalation actually works under Canada’s anti-money-laundering penalty regime
One provision is quoted more often than it is read. Section 4(2) of the AMP Regulation deems a series of minor violations serious once penalties reach $400,000 — and is widely treated as an escalator. The qualifier “for the purpose of section 73.21” makes it procedural: it secures a statutory appeal, not a larger penalty.
- March 2026 replaced the penalty ranges — 40 times the previous ceiling at each level — and capped combined penalties on one notice at the greater of $20 million or 3% of gross global revenue.
- Every prescribed violation now ends in a compliance agreement; refusal or a missed deadline produces a public compliance order, breach of which carries the greater of $30 million or 3% of group revenue.
- The exposure counsel should plan for is not the threshold but s. 9.6(1.1) — a distinct program-level violation whose evidence lies in the state of the files.
About the author
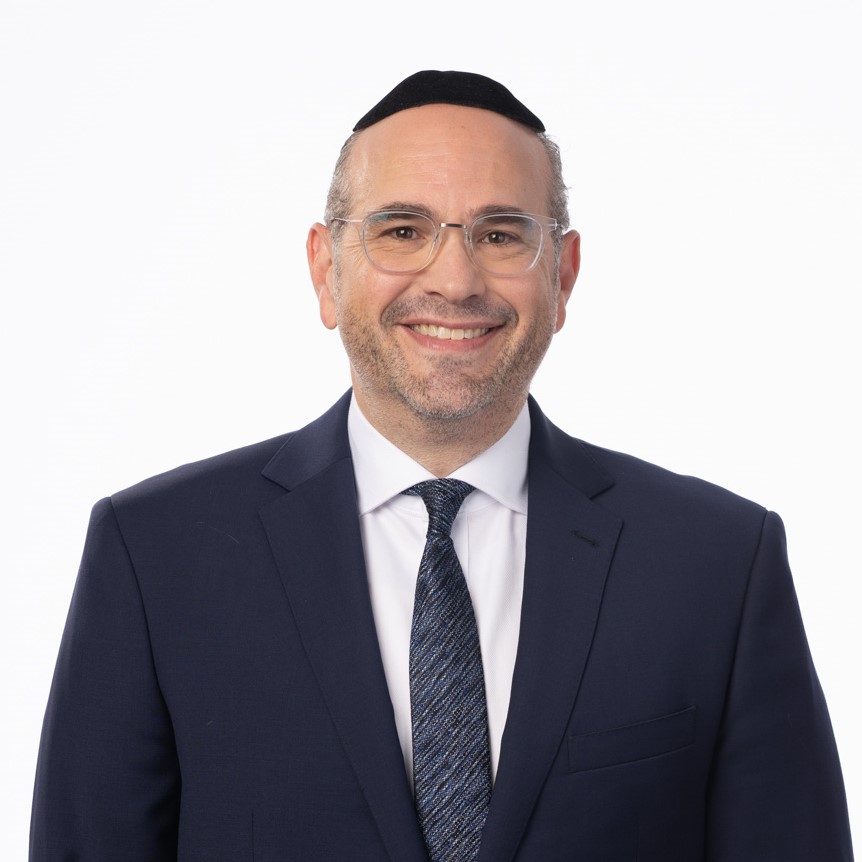
Lionel J. Perez is the CEO of CorpCentre and author of the CorpCentre Research Programme, an empirical measurement of corporate-registry compliance in Canada. A member of the Barreau du Québec, he was invited to make a submission to the Department of Finance’s 2025 consultation on extending anti-money-laundering obligations to the company service provider sector in Canada.
The measurements behind the commentary are published in full.
Every figure cited in these articles comes from a report with its method, its extract date and its limitations stated — including what it deliberately does not claim.
Read the researchNote. These articles are commentary, not legal advice. Several interpret provisions that no tribunal has yet construed, and they are offered as reasoned readings rather than settled law. The opinions are the author’s and do not necessarily reflect the views of LexisNexis Canada, Law360 Canada or their affiliates.
Disclosure. Written by Lionel J. Perez, BA, JD, LL.L, CEO of CorpCentre, which provides corporate compliance services to Canadian businesses and is a registered intermediary with Corporations Canada. In September 2025 CorpCentre was invited to participate in the Department of Finance’s consultation on company service providers. Readers should weigh that interest.